The trigger leads ban is the Homebuyers Privacy Protection Act, and it has been in force since early March 2026. A credit bureau can no longer sell the news that someone applied for a mortgage to any lender that asks. It can sell it only as a firm offer of credit, and only to a company that has the borrower's documented permission, originated or services the borrower's current mortgage, or is a bank or credit union holding a current account for them. On October 6, 2026 the Government Accountability Office published the first federal report on the law. Its headline number: at most 3.5 percent of homebuyers ever got a loan through a trigger lead offer.
In short
- At most 3.5 percent of homebuyers may have obtained a loan through an offer based on a trigger lead (GAO, 2026).
- 45.0 percent of homebuyers from 2022 to 2024 seriously considered only one lender or broker (GAO, 2026).
- After applying, a buyer could receive 30 or more messages, according to the CFPB, and in some cases 100 or more (GAO, 2026).
- Credit report costs on a conventional closing rose from about $50 in 2022 to roughly $540 in 2026, in a CHLA member survey (HousingWire, 2026).
What the trigger leads ban actually says
The law adds one paragraph to the Fair Credit Reporting Act. When a lender pulls a borrower's credit for a residential mortgage, the bureau "may not, based in whole or in part on that request, furnish a consumer report to another person" unless two things are true.
First, "the transaction consists of a firm offer of credit or insurance." Second, the company receiving the lead fits one of four descriptions:
| Who can still receive a trigger lead | Condition in the law |
|---|---|
| Any company with permission | Has certified to the bureau that it holds the consumer's authorization |
| The original lender | Originated the consumer's current residential mortgage |
| The servicer | Services the consumer's current residential mortgage |
| The consumer's bank or credit union | Is an insured depository institution or credit union holding a current account for the consumer |
The Act was enacted on September 5, 2025 and took effect 180 days later. Everyone else, the lead buyer who had never heard of the borrower until the credit pull, is out.
What the GAO found on October 6
Congress asked the GAO to look at trigger leads. Its report, GAO-27-108874, used National Survey of Mortgage Originations data from 2022 to 2024. Four findings matter to anyone who originates in Michigan.
Trigger leads rarely produced a loan. "We estimate that, at most, 3.5 percent of homebuyers may have obtained a loan through an offer based on a trigger lead." The argument for keeping them was comparison shopping. The data says that shopping mostly did not happen through them.
Most buyers do not shop much anyway. The GAO estimates 45.0 percent of homebuyers seriously considered only one lender or broker, and at most 31.7 percent applied to more than one. The first conversation tends to be the one that closes.
The volume was the complaint. The number of messages after an application "could reach 30 or more, according to CFPB, and in some cases 100 or more, according to a mortgage lender." The GAO identified more than 100 complaints likely prompted by trigger leads.
It is too early to judge the law. "Because HPPA's restrictions took effect in early March 2026, 180 days after enactment, not enough time has passed to assess the effects of the act's new restrictions." The GAO found 13 states with their own trigger lead rules. Michigan does not appear in the report.
Who loses, and who gains
The law moves the advantage to whoever already has the relationship. Before the ban, Praveen Chandramohan of Cotality told HousingWire in February 2026 that "trigger leads can represent anywhere from 10% to more than 30% of total lead volume" for direct-to-consumer and call-center lenders, while distributed retail lenders got "less than 5% of volume from trigger leads." A call center that lived on those leads has lost a channel. A loan officer whose business is referrals and past clients has lost very little, and now faces fewer strangers calling their borrowers mid-process.
The same interview flagged the side effect: internet lead costs "on some platforms have risen about 45% year over year," as lenders move budget to the leads they can still buy.
Credit report costs and the bi-merge plan
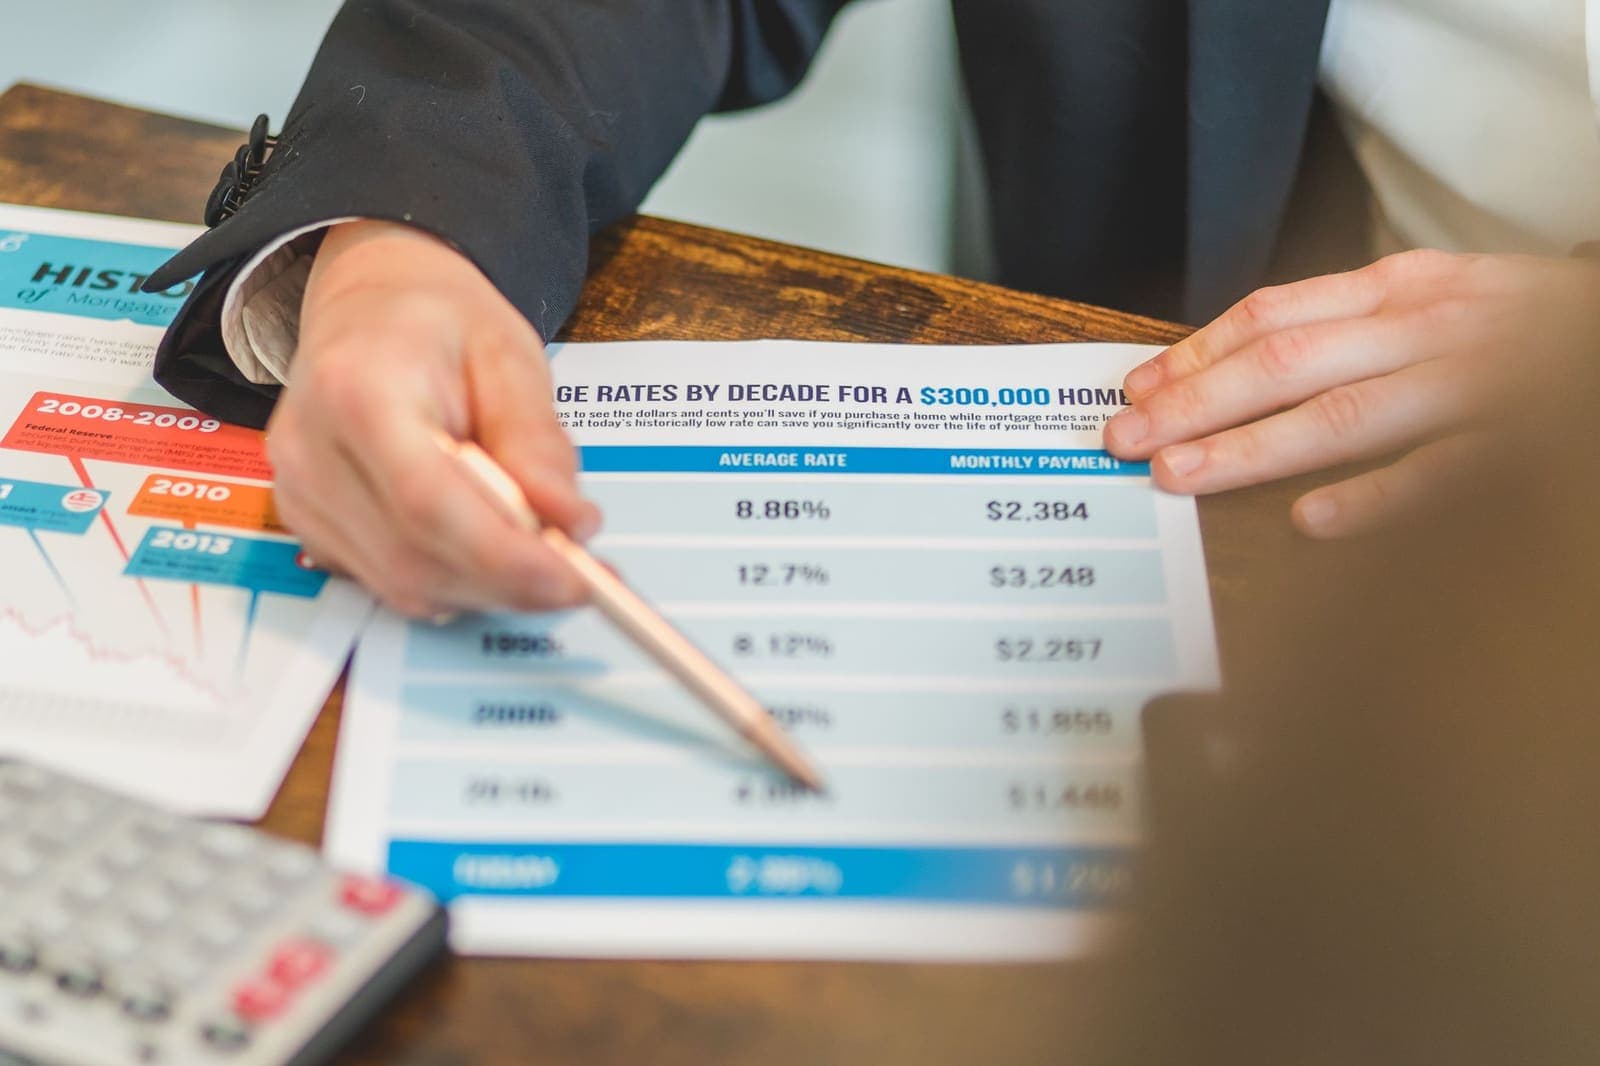
Trigger leads are one half of the credit-report story this fall. The other is cost. The Community Home Lenders of America surveyed its independent mortgage bank members and found total credit report costs on a conventional closing rose "from about $50 in 2022 to roughly $540 in 2026," according to HousingWire in April 2026. FICO disputes where that money goes.
On October 1, 2026 HousingWire, citing Bloomberg, reported that the Federal Housing Finance Agency "plans to order Fannie Mae and Freddie Mac to accept two-bureau, bi-merge credit reports instead of traditional tri-merge reports." The announcement was expected around the Mortgage Bankers Association conference in Chicago on October 12, with the change taking effect one to three months later. As of October 11 it is a report, not an order. The idea is not new: FHFA's own credit score page records the 2022 decision to permit bi-merge and the January 2025 decision to push it to "a date to be determined." Our post on VantageScore 4.0 for mortgages covers the score side of the same change.
What a Michigan loan officer should do now
- Treat your past clients as your trigger list. If you originated their current mortgage, the law still lets you receive a lead when they apply elsewhere, with a firm offer. Know who is in that group.
- Answer the first inquiry fast. With 45.0 percent of buyers considering only one lender, the first useful reply carries most of the weight. Speed matters more than volume of follow-up.
- Get permission in writing at intake. The authorization route in the law needs documentation. Make consent part of the application, not an afterthought.
- Price your lead sources again. If internet leads cost more and trigger leads are gone, compare what a reactivated past client costs against a bought lead.
- Watch the bi-merge announcement. If FHFA orders it, per-file credit cost could change within one to three months. Budget for both outcomes.
The mistake most teams make at step 1
They assume their CRM already knows who their past clients are. It usually knows names. It rarely knows whose current mortgage you originated, which loans have been refinanced away, or who stopped replying two years ago. Clean that list before you build anything on it.
Where we fit
Our lead follow-up work answers a new inquiry in seconds, runs sequences that stop the moment a borrower replies, and works an old database back to life without a loan officer having to remember who to call. It does not buy or resell credit data. For the rest of what we build for agents, teams and lenders, see real estate.
The leads you can still buy got more expensive. The ones you already have got more valuable.